Who this suits
An outright sale suits an owner who wants to step away within a defined period, take the maximum cash at closing, and stop carrying the risk of the business. It works best when the company can run without the owner day to day, or when the owner is willing to stay for a transition period of six months to two years.
It suits less well if you want to keep a say in how the company is run, if your family hopes to stay involved, or if profits are at a low point and likely to recover.
Who buys companies like yours
- Strategic buyers: companies in your industry or a neighboring one. They can pay more where they expect cost savings or cross-selling, but they will usually integrate the business into their own.
- Private equity funds: buying either a platform, a first investment in a sector, or an add-on to a company they already own. See our guide to selling to private equity.
- Family offices and independent sponsors: wealthy families or individual dealmakers who buy and hold, often for longer than a fund.
- Search funds: individuals backed by investors, looking to buy and run one company. More common for smaller businesses.
A good process reaches the right mix of all of them, in confidence.
How the process works
- Preparation (one to three months). Financials cleaned up and, ideally, reviewed by an outside accountant; adjustments to EBITDA documented; a short teaser and a detailed information memorandum written; a list of suitable buyers drawn up.
- Confidential approach (four to six weeks). Buyers sign a non-disclosure agreement before they learn the company's name or see the memorandum.
- Indications of interest. Interested buyers give a non-binding price range and outline of their terms. The best are invited to meet management.
- Management meetings and site visits. Buyers meet you and your team, usually off-site or out of hours to protect confidentiality.
- Letters of intent. Final bidders submit a letter of intent (LOI) setting out price, structure and key terms. You choose one and grant exclusivity, usually for 60 to 90 days.
- Due diligence (two to three months). The buyer's accountants, lawyers and advisors check financials, contracts, employees, environment, tax and insurance. A quality of earnings review is standard.
- Purchase agreement. Lawyers negotiate the definitive agreement: price adjustments, representations and warranties, indemnities, non-compete.
- Closing. Funds are wired, ownership transfers, and the transition begins.
A worked example
Our illustrative company, a family-owned precision fabricator in Ohio with $4.0 million of adjusted EBITDA, receives three letters of intent after a competitive process. Each looks different on the surface.
| Buyer A: competitor | Buyer B: private equity | Buyer C: family office | |
|---|---|---|---|
| Headline price | $26.0m | $25.0m | $24.0m |
| Paid at closing | $22.0m | $22.5m | $24.0m |
| Deferred or at risk | $4.0m earn-out over 3 years | $2.5m rollover equity | None |
| Owner's role | 6-month handover | CEO for 2-3 years | Chair for 1 year |
| Plans for the business | Merge into own plant | Grow and buy competitors | Keep as is |
Buyer A has the highest headline but the least certain money and the biggest change for employees. Buyer C pays least on paper but all of it in cash, with the least disruption. Which is best depends on what the owner values, which is why offers should be compared on cash at closing, risk, and what happens to the company, not on the headline. Figures are illustrative.
Thinking about a full sale in the next year or two? Start with a confidential conversation about timing and value.
Book a confidential callWhen you get paid, and what you give up
- At closing: the price, adjusted for actual debt, cash and working capital against agreed levels.
- Held back: a portion may be held in escrow for 12 to 24 months to cover claims under the purchase agreement. Where the buyer uses representation and warranty insurance, the holdback is usually much smaller.
- Later: any earn-out or seller note, if agreed.
- What you give up: ownership and control from day one, and usually a commitment not to compete for several years.
- What you sign up to: statements about the business (representations and warranties) and responsibility if they turn out to be wrong, within agreed limits.
Tax and legal points to raise with your advisors
This is not tax advice. Questions for your advisors, ideally a year before a sale:
- Asset or stock sale: the structure can change your after-tax proceeds by millions. See our guide to asset and stock sales.
- Allocation of the price between equipment, goodwill and non-compete payments affects how each part is taxed.
- State taxes, and where you live when the sale closes.
- Estate and gift planning: transferring shares to family trusts is far more effective before a deal is agreed.
- Real estate: whether to sell the property with the business or keep it and lease it to the buyer.
How ExitBuy helps
We prepare the company and its story for buyers, identify the strategic buyers, funds and family offices most likely to pay well for it, approach them confidentially and run a competitive process. We then compare offers on what you will actually receive and the risks you keep, negotiate the letter of intent before exclusivity, and manage due diligence through to closing, so you can keep running the business while it is being sold.
Frequently asked questions
How long does it take to sell a business?
Typically six to nine months from preparation to closing, longer if the financials need work first.
Will my employees find out?
Not until you decide to tell them. Buyers sign confidentiality agreements, and meetings are arranged discreetly. Most owners tell key managers during the process and everyone else at closing.
Do I need to stay after the sale?
Most buyers ask for a transition period, from a few months to two years. The length and your role are negotiable.
Should I talk to a buyer who approaches me directly?
Listen, but don't negotiate alone. A single unsolicited buyer has no competition, and the first price is rarely the best.
What are representations and warranties?
Formal statements about the business, for example that the accounts are accurate and there are no undisclosed lawsuits. If one proves untrue, the buyer may claim against you, within limits set in the agreement.
What fees should I expect?
Advisors' success fees, lawyers and accountants typically add up to a few percent of the price for a company this size. Ask for fee terms in writing at the start.
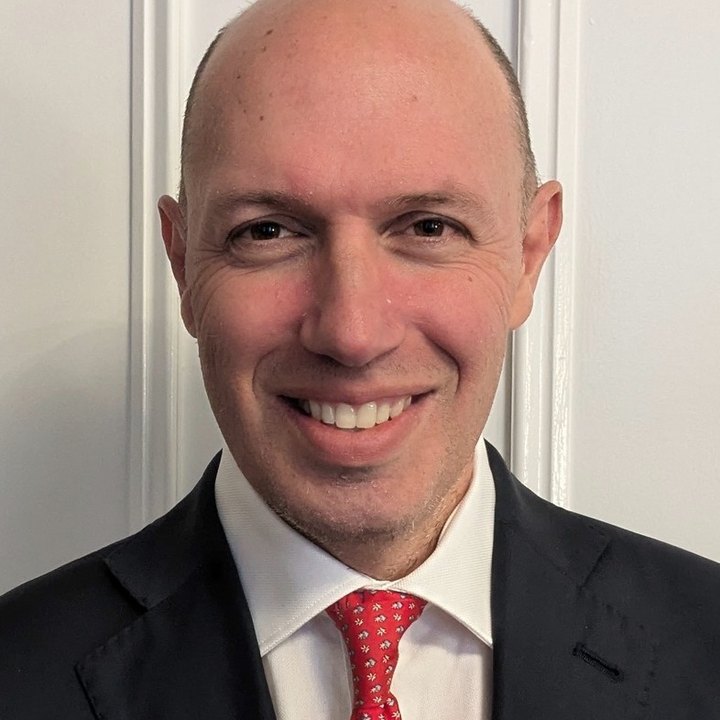
Mauro Terrinoni, CFA, founder of ExitBuy Co. 25 years in investment banking and private equity, including at JP Morgan, Citigroup and Fortress Investment Group, and has bought, run and sold a company as its owner.
General information only, not investment, legal or tax advice. Figures are illustrative. Tax rules change; confirm current law with your own advisors.