Who this suits
An MBO suits an owner who has a strong, experienced team, wants continuity for employees and customers, and is willing to help finance the sale. It works best when the managers already run the business day to day, and when profits are steady enough to support debt.
It suits less well if the business depends on you more than on the team, if the managers have never run the company without you, or if you need the highest possible price in cash at closing.
How it works
- The team expresses interest, or you invite them to consider it.
- A price is agreed, ideally supported by an independent valuation and, better still, tested against outside interest.
- The financing is assembled: bank debt against the company's cash flow, the managers' own investment, a seller note from you, and often equity from a financial backer.
- A new holding company buys your shares, with the managers as owners alongside any backer.
- You are paid: cash at closing from the bank and backer, and the seller note over time with interest.
- You step back, often staying on as an advisor or board member for a period.
Sponsored or self-funded? In a sponsored MBO, a private equity fund or family office provides most of the equity and takes majority control, with managers owning a meaningful minority. It pays more at closing but brings a new controlling owner. In a self-funded MBO, the managers own the company outright, financed by the bank and you, which usually means a larger seller note and more risk for you.
A worked example
Our illustrative company is valued at $24 million. Two senior managers want to buy it. Here are two ways it could be financed.
| Self-funded MBO | Sponsored MBO | |
|---|---|---|
| Bank debt | $9.0m | $10.0m |
| Managers' own investment | $1.0m | $1.0m |
| Equity from a private equity backer | none | $11.0m |
| Seller note from you, over 5-7 years with interest | $14.0m | $2.0m |
| Your cash at closing | $10.0m | $22.0m |
| Who controls the company | The managers | The backer, with managers as partners |
The self-funded route keeps the company entirely in the managers' hands, but leaves you as the company's largest lender for years, behind the bank. The sponsored route pays you far more at closing and brings in more capital, but adds a new controlling owner. Figures are illustrative and before fees and tax.
Thinking of selling to your managers? Let's work out what they could realistically finance, and what you would receive.
Book a confidential callMaking it fair to both sides
An MBO has a built-in tension: the buyers know the business better than anyone, including, in some respects, you. Good practice protects both sides:
- Independent valuation. An outside valuation, or better, real interest from outside buyers, gives both sides confidence in the price.
- Separate advisors. You and the management team each need your own advisors. They are on the other side of this transaction.
- Keep running the business properly. Agree how the company will be managed between the agreement and closing, so results are not affected either way.
- Seller note protections. Interest rate, repayment schedule, security, limits on dividends to the new owners until you are repaid, and the right to information.
- A plan for the future. Who will replace each manager's current role? Lenders and backers will ask.
What you give up, and the risks
- Price: managers and their backers are price-disciplined, and without competition the price may be lower than an outside buyer would pay.
- Timing: in a self-funded MBO, much of the price arrives over several years.
- Repayment risk: your seller note ranks behind the bank. If the business struggles, your payments can be delayed or reduced.
- Relationships: negotiating price with people you have worked with for years can be uncomfortable. Advisors on both sides help keep it professional.
Tax and legal points to raise with your advisors
This is not tax advice. Questions for your advisors:
- Installment sale treatment of the seller note may spread your capital gains tax over the years you are paid.
- Asset or stock sale and the allocation of the price. See our guide to asset and stock sales.
- An ESOP may be worth comparing: it can offer tax benefits an MBO does not, and can be combined with management equity incentives.
- Employment and non-compete terms for you after closing.
How ExitBuy helps
We help you test whether the management team's offer is fair, by valuing the company independently and, where appropriate, gauging outside interest discreetly. We can introduce the team to banks and to private equity firms and family offices that back management teams, structure the seller note and its protections, and negotiate on your behalf so working relationships survive the transaction.
Frequently asked questions
Can my managers afford to buy the company?
Rarely from their own savings. Bank debt, a seller note and a financial backer make up the difference. Managers typically invest a meaningful but affordable amount of their own money.
Will I get less than from an outside buyer?
Often somewhat less, especially without competition. A sponsored MBO, or inviting outside buyers alongside the management team, narrows the gap.
How long will I be financing the deal?
In a self-funded MBO, seller notes commonly run five to seven years.
Should I tell the managers about outside interest?
Handle it carefully with your advisor. A fair process can include the management team as one of several bidders.
What if the managers can't agree among themselves?
It happens. A clear lead buyer and a written agreement between the managers early in the process avoid surprises.
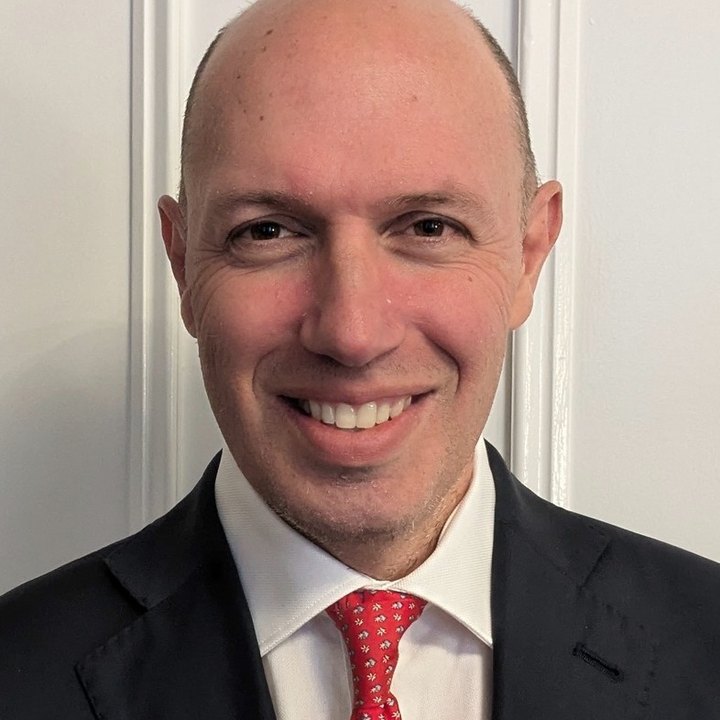
Mauro Terrinoni, CFA, founder of ExitBuy Co. 25 years in investment banking and private equity, including at JP Morgan, Citigroup and Fortress Investment Group, and has bought, run and sold a company as its owner.
General information only, not investment, legal or tax advice. Figures are illustrative. Tax rules change; confirm current law with your own advisors.