Who this suits
A majority recapitalization suits an owner who wants to secure the family's wealth now but is not ready to walk away, and who believes the company can grow faster with more capital, better systems or acquisitions. It also suits owners whose children or senior managers want to stay involved under a professional partner.
It suits less well if you want to keep control (see our guide to minority investment), if you would struggle to report to a board, or if you want a complete exit within a year or two.
How it works
- The investor values the whole company, the same way a buyer would for a full sale.
- It buys a majority stake through a new holding company, funded with its own equity and usually some bank debt.
- You reinvest part of your proceeds in the new holding company (rolling over equity), keeping a minority stake, commonly 20-40%.
- A new board takes control, with the investor holding most seats and you holding one or more.
- The company grows, often by acquiring smaller competitors with the investor's capital.
- The investor sells after four to seven years. You sell your stake alongside them, on the same terms: the second bite.
A majority recapitalization is, in effect, a private-equity buyout in which the owner keeps a larger stake than usual. See our guide to selling to private equity for how the debt and the fund's role work.
A worked example
Our illustrative company, valued at $24 million, is bought by a fund using $10 million of debt, so the equity is worth $14 million. The owner keeps 30% of the equity by rolling $4.2 million, and receives the rest of the price in cash.
| At closing | Five years later, if things go well | Five years later, if they don't | |
|---|---|---|---|
| Company EBITDA | $4.0m | $6.0m (including add-ons) | $3.5m |
| Sale value | $24.0m | $39.0m (6.5x) | $19.3m (5.5x) |
| Debt outstanding | $10.0m | $8.0m (some used for add-ons) | $6.0m |
| Equity value | $14.0m | $31.0m | $13.3m |
| Owner's 30% stake | $4.2m rolled | about $9.3m | about $4.0m |
| Owner's cash at closing | $19.8m |
In the good case, the owner receives about $29 million in total, $5 million more than selling outright. In the weaker case, about $23.8 million, roughly what a full sale would have paid, though years later. A management incentive pool, fees and taxes would reduce these figures; the shape is what matters. Larger companies tend to sell at higher multiples, which is part of the case for growing through acquisitions.
Interested in taking money off the table while keeping a stake in what comes next? Let's look at what that could mean for you.
Book a confidential callWhat you give up, and what to negotiate
As a minority owner, your protections come from the shareholders' agreement. These are the terms that matter most:
- Same price, same securities. Your rolled shares should be bought at the same price per share as the investor's, in the same class. Watch for preferred shares that give the investor a priority return ahead of you.
- Tag-along rights. When the investor sells, you can sell on the same terms.
- Board seat and information rights. Monthly accounts and a vote on the board.
- Consent rights on key decisions. For example, issuing new shares at a lower price, transactions with the investor's other companies, or changing the business fundamentally.
- Protection against dilution. The right to take part in new funding rounds so your percentage is not squeezed.
- Leverage limits. How much more debt the company can take on without your agreement.
- Your role and leaving terms. What happens to your shares if you step down, retire or are asked to leave.
- Fees. Management or transaction fees the investor charges the company reduce the value of everyone's equity.
Tax points to raise with your advisor
This is not tax advice. Questions for your tax advisor:
- Deferring tax on the rollover. The rolled portion can usually be structured so you pay no tax on it until the eventual sale. This must be built into the deal structure from the start.
- Asset or stock treatment of the portion you sell, and its allocation. See our guide to asset and stock sales.
- Gifting part of the rolled stake to family trusts before its value grows can be efficient for estate planning.
How ExitBuy helps
We find investors suited to a partnership with you, not just the highest bidder, and run a competitive process so price and terms are tested against each other. We negotiate the shareholders' agreement terms above with the same attention as the price, because your rolled stake depends on them, and help you assess each investor's plans, track record and how it has treated founders in past deals.
Frequently asked questions
How much should I keep?
Most owners keep 20-40%. Keeping more means more upside but less cash today and more exposure to the company's debt.
Will I still run the company?
Often yes, at least for a few years. Many owners stay as CEO, others become chair while a new CEO is hired. Agree it upfront.
What is a "second bite of the apple"?
The payout on your remaining stake when the investor sells. It can be larger than the first, but is never guaranteed.
Who decides when the company is sold again?
The majority investor, within limits set in the shareholders' agreement. Ask each bidder about its typical holding period.
Can my children keep a stake too?
Yes. Family members can roll equity or receive shares, subject to the investor's agreement and estate planning.
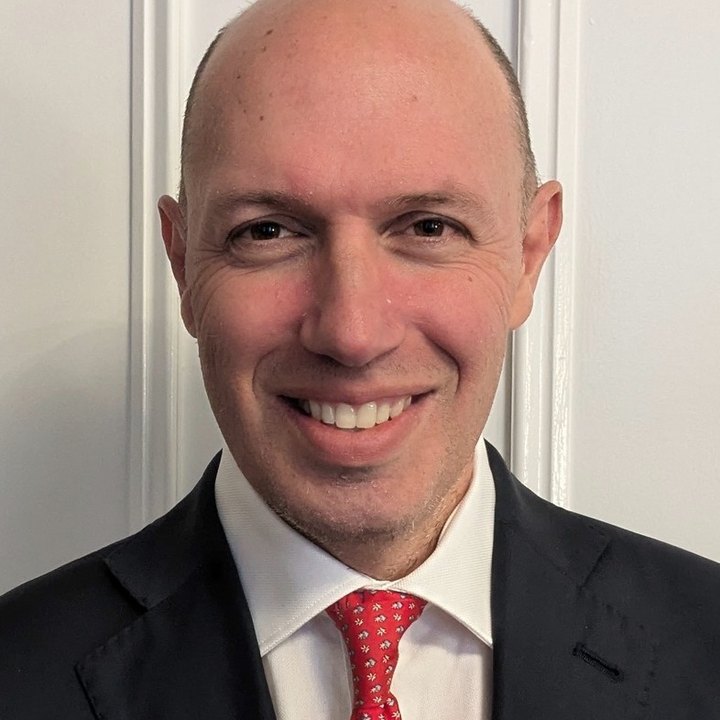
Mauro Terrinoni, CFA, founder of ExitBuy Co. 25 years in investment banking and private equity, including at JP Morgan, Citigroup and Fortress Investment Group, and has bought, run and sold a company as its owner.
General information only, not investment, legal or tax advice. Figures are illustrative. Tax rules change; confirm current law with your own advisors.