Who this suits
A minority investment suits an owner who wants to diversify the family's wealth, fund a specific plan (an acquisition, a new plant, buying out a partner or sibling) or bring in an experienced partner, without handing over control. It works well for growing, profitable companies whose owner plans to stay for years.
It suits less well if you want to step back soon, since the investor is backing you personally, or if you are not ready to share information and certain decisions with a partner.
Who invests
- Family offices: often patient, flexible on timing, and comfortable with minority positions.
- Minority-focused private equity funds: more structured, with defined returns and exit timing.
- Independent sponsors: individual dealmakers raising capital deal by deal.
- Mezzanine and SBIC funds: lend money with a small equity stake attached, a hybrid between debt and equity.
- Strategic investors: a supplier, customer or larger company taking a stake, sometimes as a step towards a later purchase.
How it works
- Decide what the money is for. Cash to you (a secondary sale), new capital for the company (a primary investment), or a mix.
- Agree a valuation. Minority stakes often price below a pro-rata share of a full-control sale, because the investor cannot control the company or decide when to sell.
- Agree the structure. Often preferred shares, which rank ahead of common shares in a sale and may carry a minimum return.
- Sign a shareholders' agreement setting out board seats, consent rights and how and when the investor can exit.
- Run the company together, with regular reporting and board meetings.
- Investor exits after five to seven years: by selling to you, to a new investor, or alongside you in a sale of the whole company.
A worked example
Our illustrative company is worth $24 million in a full sale. An investor buys 30% from the owner for $6.6 million, equal to $22 million for the whole company, a discount reflecting the lack of control. The investor receives preferred shares that guarantee it at least its money back in a sale (a 1x liquidation preference), and the right to require a sale or buyback after six years.
| Six years later, company sold for | Investor receives | Owner receives | Owner's total including the $6.6m |
|---|---|---|---|
| $33.0m (growth plan works) | $9.9m (30%) | $23.1m | $29.7m |
| $24.0m (flat) | $7.2m (30%) | $16.8m | $23.4m |
| $18.0m (weaker) | $6.6m (preference applies) | $11.4m | $18.0m |
The owner kept control for six years and took $6.6 million out early. In the weaker case, the preference means the investor gets its money back before the owner shares in the sale. That is why preference terms are worth negotiating as hard as the price. Figures are illustrative, debt-free, and before fees and tax.
Want to take some value off the table without giving up control? Let's look at who would invest, and on what terms.
Book a confidential callWhat investors will ask for
Minority investors cannot outvote you, so they protect themselves through the agreement. Expect requests for:
- A board seat, sometimes two, and monthly financial reporting.
- Consent rights over major decisions: selling the company, large acquisitions, new debt above a limit, issuing new shares, changing the business, related-party transactions.
- A liquidation preference that returns their money first in a sale, sometimes with a minimum annual return.
- An exit route: the right to require you to buy them out, or to sell the whole company (a put or drag-along), after a set number of years.
- Tag-along and pre-emption rights, so they can sell alongside you and keep their percentage.
What to negotiate
- Price versus structure. A higher valuation with heavy preferences can be worse than a lower one with ordinary shares. Compare outcomes across scenarios, as in the table above.
- Narrow consent rights. Limit them to genuinely major decisions so you can run the business day to day.
- A realistic exit timetable, and the right to choose how the investor exits, so you are not forced to sell the company at a bad moment.
- What the investor brings beyond money: sector contacts, acquisition experience, board experience. Ask to speak to owners they have backed before.
Tax points to raise with your advisor
This is not tax advice. Questions for your tax advisor:
- Selling existing shares (secondary) is generally taxed as capital gain; money invested into the company (primary) is not taxed to you but dilutes your stake.
- Bringing in an investor can affect S corporation status, since S corporations cannot have corporate or fund shareholders. A restructuring may be needed first.
- Timing gifts to family trusts before the investment, while values are lower, can help estate planning.
How ExitBuy helps
We identify the family offices and minority investors that suit your goals, run a competitive process, and compare offers on outcomes, not just headline valuation: how each structure pays out if the company does well, stays flat or struggles. We negotiate the shareholders' agreement so you keep the freedom to run your business.
Frequently asked questions
Will a minority investor pay full value?
Usually somewhat less per share than a buyer of the whole company, because control is worth something. Strong growth and competition between investors narrow the gap.
Do I keep control?
Yes, of day-to-day running and most decisions. The investor will have a veto over a short list of major ones.
How does the investor get its money back?
Through a sale of the whole company, a buyback by you or the company, or a sale of its stake to a new investor, usually within five to seven years.
Can I use the money to buy out a partner or sibling?
Yes. It is a common reason for a minority investment, and keeps the business in the family's control.
Is this the same as borrowing?
No. A loan must be repaid with interest whatever happens; an investor shares in both the upside and the risk. A leveraged recapitalization is the borrowing alternative.
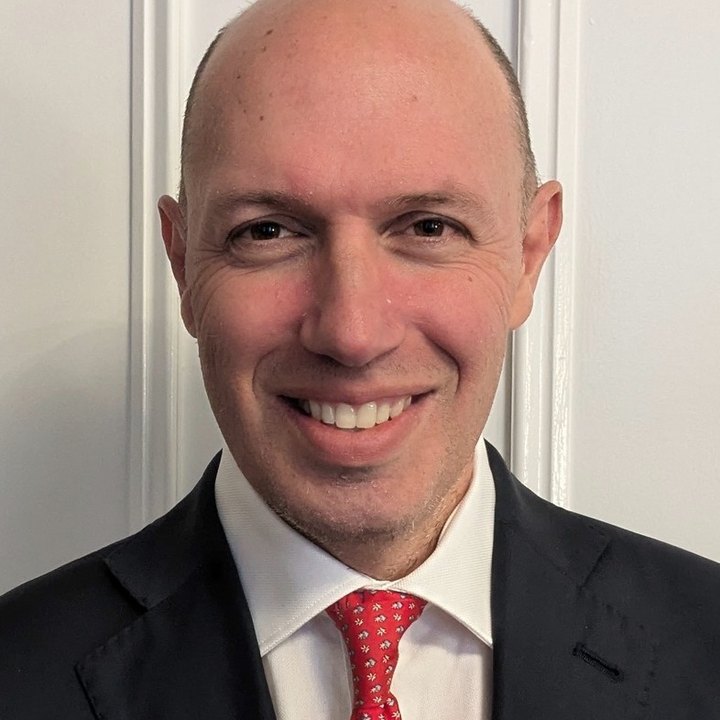
Mauro Terrinoni, CFA, founder of ExitBuy Co. 25 years in investment banking and private equity, including at JP Morgan, Citigroup and Fortress Investment Group, and has bought, run and sold a company as its owner.
General information only, not investment, legal or tax advice. Figures are illustrative. Tax rules change; confirm current law with your own advisors.