Who is buying
Private equity platforms. A fund buys one shop as a platform, then adds others around it. For the first business bought in a sector, the fund is buying your management team as much as your profits, which usually means a higher price and a request that you stay. For later additions, they are buying capacity, customers or a capability they lack.
Strategic acquirers. A larger manufacturer buying capability it would otherwise have to build: a process it currently outsources, a certification it does not hold, capacity in a region where it is short, or a customer relationship it wants.
Employee-owned manufacturers. A growing category. An ESOP-owned company acquiring a smaller shop can be an attractive home for an owner who cares what happens to the workforce.
Family offices and independent sponsors. Patient capital, often comfortable with a longer hold and a seller who wants to stay involved.
What moves the price in this sector
Buyers in metalworking and industrial manufacturing price risk more than they price revenue. The things that move your multiple up or down:
- End markets. Aerospace, defense and medical device work is priced above general industrial, because the qualification barriers that make it hard to win also make it hard to lose.
- Certifications and approvals. AS9100, ISO 13485, ITAR registration, Nadcap and customer-specific approvals are assets. They take years to obtain and transfer with the business.
- Customer concentration. The single most common reason a price is cut. One customer above about 15-20% of sales will be discussed; above 40% it will change the structure, often introducing an earn-out.
- Repeat and contract work against job-shop quotes. Released blanket orders and long-term agreements are valued well above work that is re-quoted every time.
- Equipment age and capacity. A buyer prices the capital expenditure it will have to make in the first two years. Multi-axis and well-maintained equipment with capacity to grow into is worth more than a full shop that needs reinvestment.
- The workforce, and whether it stays. Skilled machinists and programmers are the constraint on growth in this sector. Low turnover and a working apprenticeship or training path are real value.
- Whether the business runs without you. If you are still quoting, programming or holding the key customer relationships, that is the first thing a buyer prices down.
For context, GF Data reports average multiples of 6 to 7 times EBITDA for private-equity deals involving companies valued at $10-25 million, though this varies considerably across sectors and company size.
Wondering what a buyer would pay for your shop, and which buyers are active in your niche? Start with a confidential conversation.
Book a confidential callWhat buyers examine in diligence
Expect these to be opened early, and prepare them before you go to market rather than during:
- Quality system documentation, audit history and any open corrective actions.
- Customer agreements, blanket orders and the real terms behind them, including price escalation and termination rights.
- A part-level or program-level view of margin. Buyers increasingly want to see which work actually makes money.
- Equipment schedule with age, condition, maintenance history and remaining useful life.
- Environmental matters, particularly where finishing, plating, coating or solvent use is involved. These can delay a closing more than anything else in this sector.
- Workforce: turnover, open positions, union status, and how dependent output is on a handful of people.
- Real estate, and whether it is sold with the business or leased to the buyer.
How ExitBuy helps
Most owners in this sector meet one buyer and negotiate alone against a firm that does this every month. We identify the platforms, strategic acquirers and employee-owned buyers actually active in your niche and size range, approach them confidentially, and run a process where several are considering the business at the same time. We then compare what each offer actually pays you and what risk you keep.
The first consultation is free and carries no obligation.
Frequently asked questions
A private equity firm has approached me directly. Should I engage?
You can, but understand what it means. A single buyer negotiating alone sets the price. Finding out who else is active costs you a conversation.
My business depends on one large customer. Is it sellable?
Yes, though concentration will shape the structure as much as the price. The length and depth of the relationship matters more than the percentage alone.
Will a buyer keep my people?
A platform buying for growth needs the workforce and rarely makes large cuts. A strategic buyer adding capacity near an existing plant is a different conversation, and one worth having before you sign anything.
Should I sell the building too?
Often not. Many owners keep the real estate and lease it to the buyer, which can suit both sides. It should be decided early because it changes the price.
How long does it take?
Typically six to nine months from preparing materials to closing.
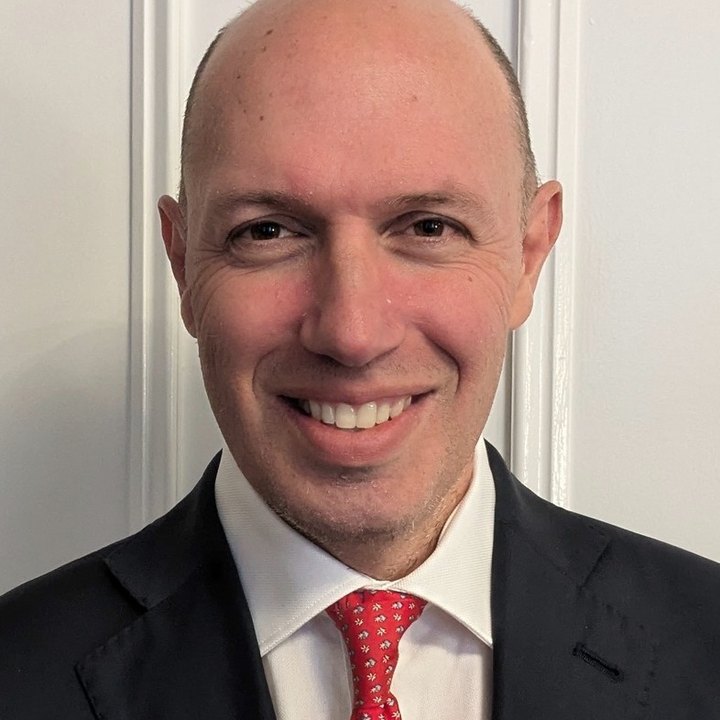
Mauro Terrinoni, CFA, founder of ExitBuy Co. 25 years in investment banking and private equity, including at JP Morgan, Citigroup and Fortress Investment Group, and has bought, run and sold a company as its owner.
General information only, not investment, legal or tax advice. Figures are illustrative. Market conditions change; confirm current terms with your own advisors.