Who is buying
Private equity platforms and their add-ons. The dominant buyer. A fund builds a platform in one region, then buys contractors nearby to add density, trades or recurring service revenue. Because these buyers are acquiring continuously, they are quick, well-financed and experienced, and they know exactly what they will pay.
Strategic acquirers. Larger regional contractors expanding into a new territory or a trade they do not currently offer.
Utilities, OEMs and distributors, occasionally, moving downstream into service.
Management buy-outs, which suit this sector unusually well. Contracting businesses often have a capable operations lead who knows the customers, and lenders understand the cash flows.
What moves the price in this sector
- Service and maintenance against new construction. This is the single biggest driver. Recurring maintenance agreements are valued far above project work, because they are predictable, higher margin and stickier. A business that is mostly new-build project work is priced quite differently from one with a large maintenance base.
- The size and renewal rate of the maintenance book. Buyers will ask for contract counts, renewal rates and average contract value, and will test them.
- Commercial against residential mix, and whether the customer base is concentrated in a few property owners or spread across many.
- Licensing. Which licences are held, in whose name, and whether they transfer. A business whose licence sits with a single individual who plans to retire is a problem to solve before going to market, not during.
- Technician retention. Labour is the binding constraint in this sector. Turnover, wage levels, and whether you have a working apprenticeship pipeline all affect what a buyer will pay.
- Work in progress and over/under billings. Contracting accounting is where valuations go wrong. Buyers scrutinise percentage-of-completion estimates closely.
- Warranty and callback history, and any open claims or litigation.
For context, GF Data reports average multiples of 6 to 7 times EBITDA for private-equity deals involving companies valued at $10-25 million, though this varies considerably across sectors and company size.
Being approached by a consolidator? Find out what the business is worth and who else is buying before you reply.
Book a confidential callWhat buyers examine in diligence
- The maintenance agreement file, contract by contract, with renewal history.
- Job-level profitability over several years, and how accurate your completion estimates proved against final outcomes.
- Licensing, bonding capacity and insurance history, including experience modification rate.
- Technician roster, tenure, pay, and the cost of replacing the people who matter.
- Fleet age, condition and the capital expenditure coming in the next two years.
- Backlog, with a view on which of it is genuinely committed.
- Any union agreements and the obligations that come with them, including multiemployer pension exposure.
How ExitBuy helps
Owners in this sector are rarely short of approaches. What they lack is a view of what the business is worth to the buyers who did not write, and leverage over the one who did. We identify the platforms and strategic buyers active in your trade, region and size range, approach them confidentially, and create a process where several are competing at once. We then compare offers on what you actually receive, what you keep at risk through rollover or earn-out, and what happens to your people.
The first consultation is free and carries no obligation.
Frequently asked questions
A consolidator has made me an offer. Is it a good one?
It may be. There is no way to know without comparing it against what other buyers would pay, which is exactly what a single-buyer negotiation prevents.
Is my business too small for private equity?
Many platforms buy add-ons well below $2 million of EBITDA. Size affects who buys and on what terms rather than whether a sale is possible.
What happens to my technicians?
Platforms buying for growth generally need every technician and often improve pay and benefits. Integration usually touches back-office functions first. Ask each bidder directly, and make the answer part of the negotiation.
I do mostly new construction. Does that hurt?
It changes the price and the structure, and it makes the buyer set matter more. Some buyers want project capability; the consolidators generally want service.
Can I sell to my operations manager instead?
Often yes. A management buy-out suits this sector, and it is worth pricing against an outside sale rather than choosing blind.
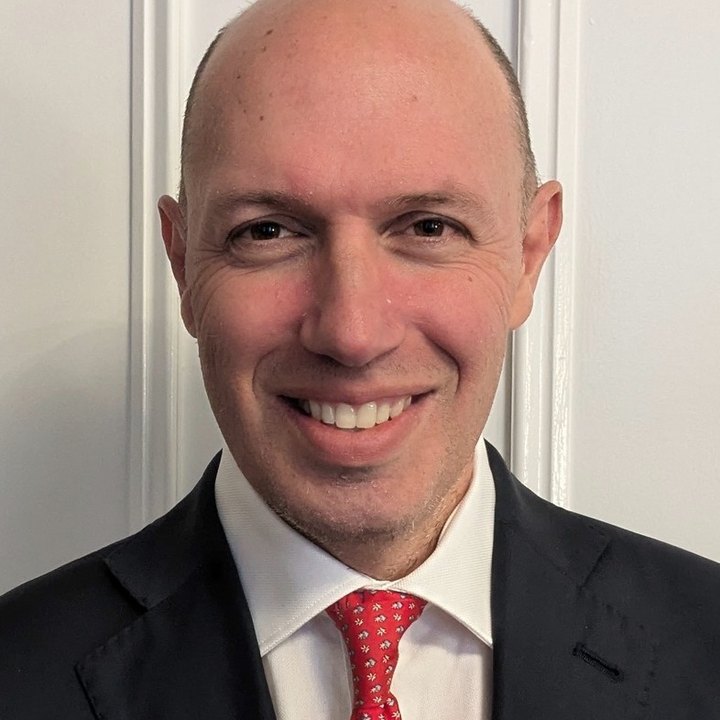
Mauro Terrinoni, CFA, founder of ExitBuy Co. 25 years in investment banking and private equity, including at JP Morgan, Citigroup and Fortress Investment Group, and has bought, run and sold a company as its owner.
General information only, not investment, legal or tax advice. Figures are illustrative. Market conditions change; confirm current terms with your own advisors.